Disclosure: This post has affiliate links. Arocol may earn a small commission at no extra cost to you. As an Amazon Associate I earn from qualifying purchases. Read our disclosure.
From Mahalaya to Bhai Dooj, the next few weeks are the happiest time of the year in most Indian homes. New clothes, pandal hopping, sweets, guests, gifts, gold on Dhanteras, a new phone because “the sale is on”. And then, sometime in late November, the credit card bill arrives and the happiness goes quiet.
It doesn’t have to be like that. You don’t need to cut the celebration. You need a plan made before the shopping starts, not after. This guide shows you how to make a simple festive budget in an evening, how to avoid the traps that turn one month of fun into six months of EMIs, and how to keep the joy without the debt.
Why festive spending gets out of hand
Most of us don’t overspend on one big thing. We overspend on fifty small things that each felt reasonable. ₹1,500 for a kurta here, ₹800 for sweets there, ₹2,000 for a gift for a cousin’s family, a restaurant dinner with friends, a cab home at midnight. None of them is a mistake on its own. Together, they can easily cross a full month’s salary.
The festive season also has three things working against your wallet at the same time:
- Big sales and “limited time” offers that make you feel you’ll lose money if you don’t buy now.
- Easy credit: no-cost EMI, Buy Now Pay Later and credit card limits that look like free money.
- Social pressure: relatives, colleagues and Instagram all seem to be buying something new.
A festive budget doesn’t fight any of this with willpower. It just decides the numbers in advance, when you’re calm, so you don’t have to decide in the middle of a sale.
Step 1: Decide one total amount for the whole season
Start with a single number: how much can you spend from Durga Puja to Diwali without touching your emergency fund and without borrowing?
To find it, look at three sources only:
- Money you’ve already saved for festivals. If you kept a small amount aside every month this year, great. That’s your first source.
- Your festive bonus, if your company gives one. Don’t spend all of it. A simple rule is to use about half for the festivals and send the rest to savings or investments.
- What’s left from this month’s salary after rent, EMIs, bills, groceries and your regular SIP.
Add these up. That’s your festive budget. Not your credit card limit. Not what your neighbour spent. Just money you actually have.
Here’s an example. Say a family in Guwahati has ₹15,000 saved for festivals, gets a ₹20,000 bonus (and uses half, ₹10,000), and can spare ₹5,000 from this month’s salary. Their festive budget for the whole season is ₹30,000. Everything that follows has to fit inside that number.
If you want help building a regular monthly budget too, our simple guide on where your salary goes every month walks you through it.
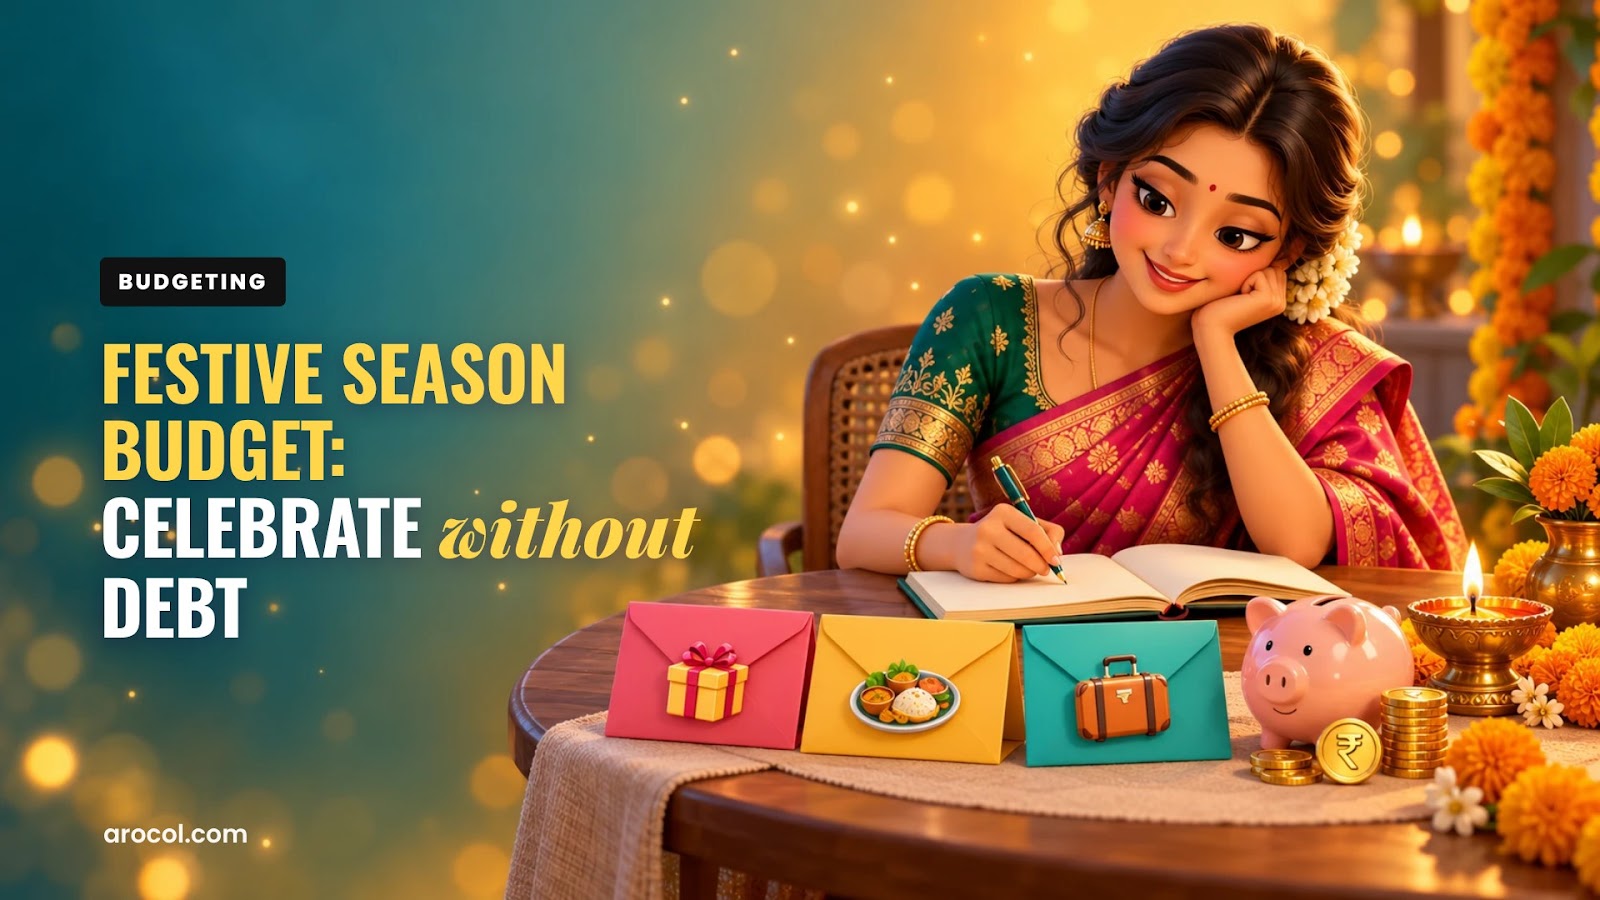
Step 2: Split your festive budget into three pots
One big number is easy to blow through. Three smaller pots are much easier to control.

- Pot 1: Gifts and clothes (about 40%). New clothes for the family, gifts for relatives, friends, helpers and colleagues.
- Pot 2: Food and guests (about 30%). Sweets, special meals at home, guests, eating out.
- Pot 3: Puja, travel and outings (about 30%). Puja items, donations, pandal hopping, cabs, a short trip home.
With the ₹30,000 example, that’s ₹12,000 for gifts and clothes, ₹9,000 for food and guests, and ₹9,000 for puja, travel and outings. Change the percentages to suit your family. If you’re travelling home for the festival, Pot 3 will be bigger. If you host a lot of guests, Pot 2 will be. The point is to decide now.
A practical trick: keep each pot somewhere you can see it. Some people use three envelopes of cash. Others use a separate savings account or simply a note on their phone that they update after every purchase. When a pot is empty, that category is done for the season.
Step 3: Make a list before every shopping trip
Sales are designed to make you buy things that weren’t on any list. So make the list first.
- Write down who you’re buying for and a rough amount for each person.
- For clothes, decide how many outfits each family member really needs.
- For big items (a phone, a TV, a fridge), ask one honest question: would I buy this next month at the same price? If the answer is no, the sale is the only reason, and that’s a weak reason.
- Compare the price on at least two sites, or online versus a local shop, before buying anything over ₹5,000.
Lists feel boring. They also save more money than any coupon code.
Check your festive spending every night with AI
A budget only works if you know where you are in it. But festive spending is scattered: UPI here, a card swipe there, cash at the pandal stall.
Here’s the 2-minute habit I use. Every time I spend, I type one line in my phone’s notes app: “kurta 1,450”, “sweets 600”, “auto 120”. At night I copy the whole note into ChatGPT or Gemini with this prompt:
Prompt to copy
My festive budget is ₹[total]. Pot 1 (gifts and puja) ₹[amount], Pot 2 (clothes and home) ₹[amount], Pot 3 (outings and food) ₹[amount]. Below is everything I spent so far. Put each item in the right pot, add up each pot, and tell me how much is left in each and in total. If any pot is more than 80% used, warn me clearly. Don’t give shopping advice. Here is my list: [paste]
Seeing “Pot 2: ₹600 left” stops the next impulse buy better than any willpower. Keep the list to items and amounts only. No card numbers, no bank names, no UPI IDs. If you’d like to use the same idea for your monthly salary, I’ve written about planning your whole budget with AI.
One caution: AI can add numbers wrong, especially in long lists. Glance at the totals. If something looks off, ask it to show the sum line by line.
Is no-cost EMI really free?
“No-cost EMI” is everywhere during festive sales. It sounds perfect: buy a ₹30,000 phone and pay ₹5,000 a month for six months, with no extra cost. But it’s worth knowing how it actually works.

In most no-cost EMI deals, the bank still charges interest on the loan. The seller or brand gives you a discount equal to that interest, so the two cancel out. But two things usually don’t cancel out:
- GST on the interest. GST of 18% is charged on the interest part of your EMIs, and you pay it.
- A processing fee, often a few hundred rupees plus GST, charged by the card issuer or lender.
Here’s a simple example (actual rates and fees vary by bank and deal). On a ₹30,000 purchase over six months at about 15% interest, the interest works out to roughly ₹1,330. The seller gives that back as a discount. But GST on that interest is about ₹240, and if the processing fee is ₹199 plus GST, that’s another ₹235 or so. So your “no-cost” phone actually costs around ₹475 more than its price.
That’s not a scam. It’s a small, fair cost for spreading payments. The real problems are different:
- Sometimes the full-payment price is lower than the EMI price, because the discount for paying upfront isn’t offered on EMI. Always compare the final amount.
- Several small EMIs from different purchases add up quietly and eat into next year’s salary.
- Missing even one EMI brings late fees, interest and a hit to your credit score.
Use no-cost EMI only for something you’d buy anyway, only if the total EMIs fit easily inside your monthly budget, and only after checking the real final cost on the payment page.
Credit cards: a great tool, or a festive trap
A credit card can actually save you money in the festive season, through cashback, reward points and bank offers during sales. But only if you pay the full bill by the due date. The moment you pay only the minimum due, it becomes one of the most expensive loans in India.

Credit card interest in India is commonly around 3% to 3.75% per month, which is roughly 36% to 45% a year. On a ₹40,000 festive bill, paying only the minimum can mean over ₹1,400 of interest in the first month alone, plus GST on that interest. And the interest keeps running on the unpaid amount month after month. Our guide on paying only the minimum due explains exactly how it grows.
Simple rules for using a card this season:
- Only put on the card what’s already inside your festive budget. The card is a payment method, not extra money.
- Set up autopay for the full statement amount, not the minimum.
- Check your card’s bank offers before a sale. A 10% instant discount on a planned purchase is real savings; on an unplanned one, it isn’t.
If you’re looking for a card that rewards everyday and online spending, cashback cards like the SBI Cashback Card or the HDFC Millennia Credit Card can help, but only if you pay in full every month. Compare the annual fee and the cashback caps before applying. And don’t apply just for a sale; a new card should make sense for your whole year.
Buy Now Pay Later: small amounts, big habits
BNPL buttons at checkout make it very easy to buy something today and pay “next month”. The amounts look tiny, ₹1,200 here, ₹2,500 there. But BNPL is a loan. Late payments can bring fees and can be reported to credit bureaus, which can lower your CIBIL score. Several BNPL dues falling in the same week of December can hurt more than one big bill.
If you use BNPL at all this season, keep it to one provider and one or two purchases, and treat each one as part of your festive budget, not on top of it.
Gold on Dhanteras: buy it the smart way
Buying a little gold on Dhanteras is a beautiful tradition, and it can also be a sensible investment if you do it right. Decide your gold amount as a separate line in Pot 1 or from your savings, not from leftover festive money. Jewellery has making charges, while coins, Gold ETFs and other options work differently. We compared them in our Dhanteras gold guide.
Gifts that don’t break the bank
Gifts are where festive budgets usually leak the most. A few ideas that feel thoughtful without being expensive:
- Set a gift amount per person and stick to it. Families often appreciate this when everyone does it.
- Home-made sweets or snacks in a nice box are often valued more than a shop-bought one.
- Group gifts: for a colleague or a relative, a few people can share one good gift instead of each buying something small.
- Useful gifts: a good book, a plant, a kitchen item someone actually needs. If you’re buying books or small items online, compare options on Amazon and other sites before you decide.
- For helpers and staff, a cash gift or a festive bonus is usually more useful than an object. Keep it inside Pot 1.
A festive budget for different incomes
Every family’s numbers are different, so here are three rough examples of how a festive budget can look. These are only examples to help you think, not rules.
- Single person earning ₹25,000 a month: a festive budget of ₹6,000 to ₹8,000 could cover a couple of new outfits, small gifts for family, sweets and a few outings with friends. Keep your SIP running, even if it’s small.
- Young couple earning ₹60,000 together: ₹15,000 to ₹20,000 for the season, with a bigger travel pot if you’re going home for Puja or Diwali.
- Family of four earning ₹1 lakh a month: ₹30,000 to ₹40,000, including clothes for everyone, guests at home and a small gold purchase on Dhanteras from a separate savings line.
Notice what’s common: in each case, the festive budget is decided first, it comes from money already available, and regular savings continue. That’s what keeps the celebration debt-free. If your festive budget feels too small this year, that’s useful information too. It tells you to start saving for next year’s festivals a little earlier.
Stay safe from festive scams
Scammers love festive season because people are busy, excited and shopping a lot. Fake offer links, fake delivery fees, OTP calls and “scan this QR to get a refund” messages all go up. I’ve listed the common ones and how to spot them in my festive sale shopping guide. The one rule that stops almost all of them: never share an OTP or UPI PIN, and buy only from official apps and websites you type yourself. If money is lost, see our guide to UPI and online fraud protection for what to do next.

A simple festive budget timeline
- Now (before Durga Puja): fix your total festive budget and split it into three pots. Make the gift list.
- During Durga Puja: track spending every evening. Two minutes on your phone is enough.
- Between Durga Puja and Diwali: check how much is left in each pot. Move money between pots if needed, but don’t add new money.
- Before Dhanteras and Diwali: decide big purchases and gold in advance. Compare prices and check the real cost of any EMI.
- After Diwali: pay every card bill in full, write down what you actually spent, and start saving a small amount every month for next year’s festivals.
That last step is the real secret. If you save ₹2,500 a month from January, you’ll have ₹22,500 ready by next October, and festive season will feel completely different. A simple recurring deposit or a separate savings account is enough for this. If you want, use AI to help, as we explain in our guide on planning your budget with AI.
What if you’ve already overspent?
It happens. If you’re reading this after the shopping, don’t panic and don’t ignore it.
- Add up every festive purchase, including EMIs and BNPL dues, in one list.
- Pay credit card bills in full if you possibly can. If you can’t, pay as much as you can above the minimum, and stop using that card until it’s cleared.
- Cut non-essential spending for the next two or three months and use the savings to clear the dues, starting with the one charging the highest interest.
- Don’t take a personal loan or a new card just to pay the old one unless the interest is clearly lower and you have a plan to close it.
- Next year, start a festival fund in January (see below).
Start next year’s festival fund in January
The easiest festive budget is one that’s already paid for. Festivals come on the same calendar every year, yet we treat the spending like a surprise.
Here’s the simple fix. Once this season is over, add up what you actually spent. Say it was ₹36,000. Divide it by 10, the months from January to October. That’s ₹3,600 a month.
- Open a recurring deposit in your bank app for ₹3,600 a month, starting in January, maturing in October. You’ll also earn a little interest on top.
- Or use a separate savings account or a “goal” pocket in your bank app, with an auto-transfer on salary day, so you never see that money in your spending account.
- Don’t invest it in shares or equity funds. You need it on a fixed date. A market fall in September would ruin the plan.
When October comes, all three pots are already sitting there, and your bonus can go towards your goals instead of festival bills.
If ₹3,600 feels too much, start with what you can, even ₹1,000. Any amount saved before the festival is money you won’t have to pay interest on after it.
Frequently asked questions
How much should I spend during the festive season?
There’s no single right number. A good limit is money you’ve saved for festivals, plus part of your bonus, plus what’s left from this month’s salary after essentials and savings. If you need to borrow or touch your emergency fund, you’re spending too much.
Should I use my emergency fund for festivals?
No. An emergency fund is for job loss, medical bills and real emergencies. Festivals come every year on known dates, so they should have their own savings. Read more in our guide on why you need an emergency fund.
Do festive sales really save money?
They do for things you planned to buy anyway. They don’t if they make you buy things you didn’t need. How to check whether a discount is real is in my festive sale shopping guide.
Can I use my festive bonus for investing?
Yes, and it’s a great idea to invest at least part of it. You could put part of your bonus into an index fund or add it to your PPF, while keeping the rest for the festivals.
The bottom line
A festive budget isn’t about spending less joy. It’s about choosing where your money goes before the sales choose for you. Pick one total amount, split it into three pots, make a list, pay credit cards in full, check the real cost of any EMI, and start saving for next year’s festivals in January. Then enjoy every pandal, every sweet and every diya without a single worry about December’s bills.
Recommended reads
- Where Does Your Salary Go? A Simple Budget for Indians
- Paying Only the Credit Card Minimum Due? Read This First
- Dhanteras Gold Guide: Jewellery vs Coins vs ETF vs Digital
- UPI and Online Fraud in India: How to Keep Your Money Safe
- How to Use AI to Plan Your Monthly Budget in India (Free Tools + Prompts)
This article is for general information only and isn’t financial advice. Interest rates, fees, GST and offers on credit cards, EMI and BNPL vary by bank and seller and change often. Please read the terms and the final payment page carefully before you buy, and speak to a qualified adviser for personal guidance.