Disclosure: Some links in this post are affiliate links. If you buy through them, Arocol may earn a small commission at no extra cost to you. As an Amazon Associate I earn from qualifying purchases. Read our affiliate disclosure.
“Where did my salary go?”
If you’ve asked yourself this around the 20th of every month, you’re not alone. Your salary comes in on the 1st, rent and EMIs go out, and then the money slowly leaks away through UPI payments of ₹80, ₹240 and ₹499 that you barely remember. By the end of the month, there’s nothing left to save, let alone invest.
Most budgeting advice says “track every rupee in a spreadsheet”. It works, but very few people stick with it. It’s boring, it takes time, and one missed week means you give up.
This is where AI tools like ChatGPT, Google Gemini, Microsoft Copilot and Claude can genuinely help. Not as a magic money manager, but as a patient assistant that can sort hundreds of transactions in seconds, spot where your money really goes, and help you build a budget you’ll actually follow.
In this guide, you’ll learn exactly how to use AI to plan your monthly budget in India, step by step. You’ll get ready-to-copy prompts, a real example with numbers, the privacy rules you must follow, and the mistakes AI makes that you need to watch out for.
Why use AI for budgeting at all?
Budgeting has two hard parts. The first is collecting and sorting your spending, which is slow and boring. The second is making decisions: how much to spend on what, how much to save, and what to cut. AI is very good at the first part and quite useful for the second, as long as you stay in charge.
Here’s what AI does well:
- Sorting transactions fast. Paste a masked bank statement and ask it to group spends into rent, groceries, food delivery, travel, shopping and bills. What takes you an hour takes it a few seconds.
- Spotting patterns. It can tell you that you ordered food 23 times last month, or that four streaming subscriptions renew on different dates.
- Building a plan around your real life. You can say “I live in Bengaluru, pay ₹14,000 rent, send ₹5,000 to my parents and want to start a SIP”, and get a budget built around that.
- Explaining money ideas simply. Confused about the 50/30/20 rule, an emergency fund or how a SIP works? You can ask follow-up questions as many times as you like.
- Keeping you consistent. A monthly 15-minute review with AI is much easier to stick to than a daily spreadsheet habit.
And here’s what it can’t do: it doesn’t know your full situation, it sometimes gets maths and rules wrong, and it isn’t a SEBI-registered advisor. Think of it as a smart calculator that talks, not a financial planner. We’ll come back to this.
Before you start: privacy rules you must follow

This is the most important section of this guide, so please don’t skip it. When you paste something into an AI chatbot, it leaves your phone and goes to a company’s servers. Treat it like sending a message to a stranger who is helpful but whom you don’t fully know.
Never share with any AI tool:
- Your PAN, Aadhaar, passport or voter ID number
- Bank account numbers, IFSC with account number, or full card numbers
- OTP, UPI PIN, ATM PIN, CVV, net banking or app passwords
- Your UPI ID and phone number together
- Your full name with home address
Safe to share: spending categories, rounded amounts like “about ₹4,000 on food delivery”, your goals, timelines and city, and statements where you’ve masked personal details with XXXX.
A few more habits that keep you safe:
- Mask before you paste. Delete or replace account numbers, names of people you paid, and reference numbers. You only need the date, a short description and the amount.
- Check privacy settings. Many AI apps let you turn off chat history or stop your chats being used to train their models. Look for this in settings before you start.
- Use the official app or website only. Fake “AI money assistant” apps and Telegram bots are a growing scam. If anything asks for your bank login or OTP, it’s a fraud. Our guide on UPI and online banking frauds explains the common tricks.
- Know where to report. If you’ve been cheated online, call the national cybercrime helpline 1930 immediately or report it at cybercrime.gov.in.
The 4-step AI budgeting method

The whole process takes about an hour the first time and around 15 to 30 minutes every month after that. Here’s how it works.
Step 1: Collect three months of spending
One month can be misleading. Maybe you had a wedding, a trip or a big repair. Three months gives a much more honest picture of where your money goes.
Gather these:
- Bank statement: Download it from net banking or your bank’s app. Excel or CSV is easiest to work with, but PDF also works if you copy the text.
- Credit card statements: These show online shopping, subscriptions and EMIs that don’t appear clearly in your bank statement.
- UPI history: Most UPI payments already show up in your bank statement, but the descriptions can be cryptic. Your UPI app’s history helps you work out what “UPI/DR/4829XXXX/SWIGGY” actually was.
- Cash: If you withdraw cash regularly, write down roughly what it went on.
Now mask the personal details. In a spreadsheet, delete the columns with account numbers and reference IDs. Keep only date, description and amount. Replace names of individuals with labels like “Friend”, “Maid” or “Parents”.
India is also building a safer way to share financial data called the Account Aggregator framework, regulated by the Reserve Bank of India. It lets you share your bank data with apps through consent, without giving away passwords. You can learn more at Sahamati. Some budgeting apps use it, but for chatbots, masking and pasting is still the simplest way.
Step 2: Ask AI to categorise your spending
Paste your masked transactions and use a clear prompt. The more specific you are, the better the answer. Here’s one you can copy:
“I’m sharing three months of my bank transactions from India. Personal details are masked. Please group every transaction into these categories: Rent, Groceries, Utilities and bills, Phone and internet, Transport and fuel, Food delivery and eating out, Shopping, Subscriptions, Health, Family support, EMIs and loans, Investments, Cash withdrawals, and Other. Show a table with the monthly total for each category and the three-month average. Then list anything you couldn’t categorise so I can tell you what it was.”
The last line matters. AI will guess when descriptions are unclear, and guesses can be wrong. Asking it to list unclear items lets you fix them instead of trusting a wrong total.
Once you have the table, ask follow-up questions:
- “Which three categories grew the most from month 1 to month 3?”
- “List all recurring payments and subscriptions, with the date they renew.”
- “How many times did I order food delivery each month, and what was the average order?”
- “How much did I spend in small UPI payments under ₹200?”
That last one is often a shock. Small payments for chai, snacks, autos and quick-commerce orders easily add up to ₹3,000 to ₹6,000 a month. If you’ve never looked closely, our post on where your salary goes every month explains the most common leaks.
Step 3: Plan your budget
Now that you know where the money goes, ask AI to help you decide where it should go. A good starting point is the 50/30/20 rule:
- 50% for needs: rent, groceries, bills, transport, insurance premiums and EMIs
- 30% for wants: eating out, shopping, entertainment, trips and subscriptions
- 20% for savings and investing: emergency fund, SIPs, PPF and other goals

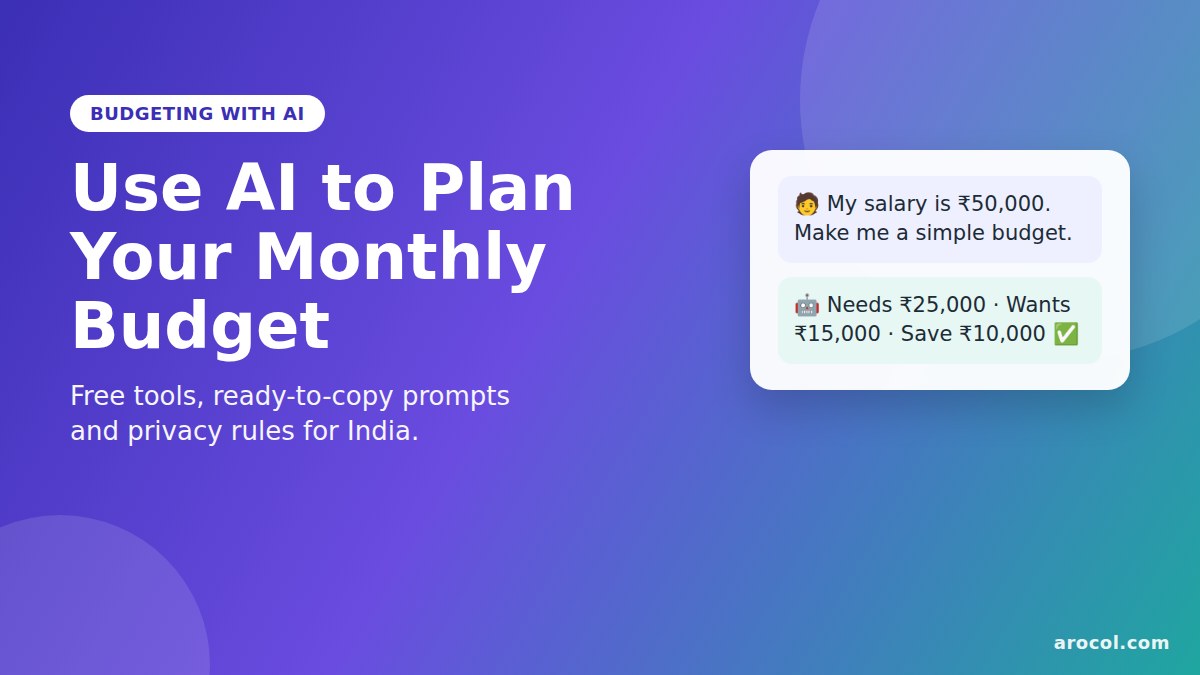
On a ₹50,000 take-home salary, that’s ₹25,000 for needs, ₹15,000 for wants and ₹10,000 for savings. It’s a starting point, not a law. If you live with your parents and don’t pay rent, you could save 30% to 40%. If you live in Mumbai and rent alone takes 40% of your salary, you might start with 10% savings and increase it over time.
Here’s a prompt to build your plan:
“My monthly take-home salary is ₹50,000. I live in Pune and pay ₹13,000 rent. Based on the spending table above, create a monthly budget using the 50/30/20 rule as a starting point, adjusted for my situation. I want to build an emergency fund of 6 months of essential expenses and start a monthly SIP. Show the budget as a table with a limit for each category, and tell me which categories I need to cut and by how much.”
Then push back. Ask “Is this realistic if I can’t reduce rent?” or “Give me a version where I save ₹12,000 a month”. The best budgets come from a few rounds of back and forth.
Step 4: Review every month
A budget only works if you check it. On the 1st of each month, paste last month’s masked transactions and ask:
“Here is my budget and last month’s transactions. Compare plan vs actual for each category in a table. Tell me where I overspent, where I stayed within limits, and suggest one realistic change for next month.”
One small change each month is far more effective than trying to fix everything at once.
A real example: how Riya found ₹6,200 a month
Let’s walk through an example. Riya is 27, works in Pune and takes home ₹45,000 a month. She shares a flat, has no loans and always felt she “should be saving more” but never had anything left. She had a ₹3,500 recurring deposit and that was it.
She pasted three months of masked bank and credit card transactions into an AI chatbot and asked it to categorise them. Here’s the three-month average it found:
| Category | Monthly average |
|---|---|
| Needs (rent share, groceries, bills, phone, transport) | ₹21,000 |
| Food delivery | ₹6,200 |
| Quick-commerce snacks and extras | ₹2,400 |
| Shopping | ₹4,100 |
| Subscriptions (4 apps) | ₹1,300 |
| Weekend outings | ₹1,800 |
| Small UPI payments she couldn’t explain | ₹4,700 |
| Recurring deposit (savings) | ₹3,500 |
| Total | ₹45,000 |
Her needs were fine at about 47% of her salary. The problem was wants and unexplained small payments, which together took more than 45%. Savings were under 8%.
After a few rounds of questions, Riya and the AI agreed on these changes:
- Cancel two subscriptions she rarely used: saves ₹600
- Cap food delivery at ₹3,500 a month, about two orders a week: saves ₹2,700
- Cap quick-commerce orders at ₹1,200: saves ₹1,200
- Set a ₹3,000 monthly limit for small UPI payments and check it weekly: saves ₹1,700
That’s ₹6,200 a month freed up, without touching rent, groceries or her weekend outings. Her savings went from ₹3,500 to ₹9,700, about 21.5% of her salary.
| Category | Before | After |
|---|---|---|
| Needs | ₹21,000 | ₹21,000 |
| Wants (food, shopping, subscriptions, outings) | ₹15,800 | ₹11,300 |
| Small UPI payments | ₹4,700 | ₹3,000 |
| Savings and investing | ₹3,500 | ₹9,700 |
She now puts ₹5,000 a month into her emergency fund until it reaches about ₹1.26 lakh (six months of her ₹21,000 essential expenses), and ₹4,700 into a monthly SIP. If that SIP earned an average of 12% a year for 15 years, it could grow to roughly ₹23 to 24 lakh. Market returns are never guaranteed, but you can try different numbers with our SIP calculator.
One important detail: when Riya first asked for totals, the AI added one month’s figures wrong by about ₹900. She only noticed because the total didn’t match her salary. Always check that the numbers add up.
15 ready-to-copy AI prompts for your money
Copy these, change the numbers to match your life, and paste them into your AI tool. Remember to mask personal details first.
Understanding your spending
- “Group these masked transactions into categories and show monthly totals and a three-month average in a table.”
- “List every recurring payment and subscription, how much it costs per year, and when it renews.”
- “Which five merchants or categories took the most money last month? Show amounts and percentage of my salary.”
- “How much did I spend on weekends compared to weekdays?”
Building a budget
- “My take-home salary is ₹[amount] and I live in [city]. Create a realistic monthly budget using 50/30/20 as a starting point, adjusted for my fixed costs: [list them].”
- “I get a ₹[amount] bonus in March. Suggest how to split it between my emergency fund, investments and something fun, with reasons.”
- “I’m a freelancer and my income varies between ₹30,000 and ₹70,000. Help me build a budget based on my lowest month.”
- “Create a simple budget I can follow in a Google Sheet, with formulas to compare plan vs actual.”
Saving and paying off debt
- “My essential expenses are ₹[amount] a month. How much should my emergency fund be, and how long will it take to build if I save ₹[amount] a month?”
- “I have credit card dues of ₹[amount] at about [rate]% a month and a personal loan of ₹[amount]. Make a payoff plan that clears the costliest debt first.”
- “I want ₹[amount] for a trip in 10 months. How much should I save each month, and where should I keep it?”
- “Suggest 10 practical ways to cut ₹3,000 a month from my spending without cutting groceries or rent.”
Learning and checking
- “Explain how a SIP works, like you’re talking to a beginner in India. Use an example with ₹2,000 a month.”
- “What questions should I ask before buying a health insurance policy for my parents?”
- “Check this budget for mistakes. Do all the categories add up to my salary? Is anything unrealistic?”
Which AI tools can you use?
You don’t need a paid app to get started. The popular general AI assistants all have free versions that are good enough for budgeting:
- ChatGPT (OpenAI)
- Google Gemini, which also works with Google Sheets
- Microsoft Copilot, which also works with Excel
- Claude (Anthropic)
They all handle the prompts above well. Pick the one you find easiest, and stick with it so your budget conversations stay in one place. Features and free limits change often, so check each tool’s current plans and privacy settings yourself.
A simple spreadsheet is still the best place to keep your actual budget. Let AI do the sorting and suggestions, and keep the final numbers in Google Sheets or Excel where you control them. Some people also like a paper budget planner, because writing things down makes spending feel more real. You can find monthly budget planner diaries on Amazon.
What AI gets wrong (and how to protect yourself)
AI tools are helpful, but they make mistakes in very confident language. Here’s what to watch for:
- Maths errors. AI chatbots can add numbers wrong, especially with long lists. Always check that totals match your salary, or recheck them in a spreadsheet.
- Outdated rules. Tax slabs, deduction limits, interest rates and investment rules change with every Budget. AI may give you last year’s rules. For tax questions, read our guide on the old vs new tax regime and confirm on the Income Tax Department’s website.
- Made-up facts. AI can invent product names, interest rates or “schemes” that don’t exist. Never invest in anything only because an AI mentioned it.
- Generic advice. It doesn’t know your health, family responsibilities or job security unless you tell it, and even then it can’t see the full picture.
- Not a registered advisor. AI is not a SEBI-registered investment advisor. For learning how investing works and checking whether an advisor is registered, the SEBI investor website is a reliable place to start.
A good rule: use AI to organise and understand, but make decisions yourself, and check anything important against an official source or a calculator.
Common mistakes people make with AI budgeting
- Pasting unmasked statements. This is the biggest risk. Always remove account numbers and personal details first.
- Making the budget too strict. If AI suggests cutting all eating out, you’ll give up within two weeks. Keep some money for things you enjoy.
- Ignoring irregular expenses. Insurance premiums, school fees, festivals like Diwali and annual subscriptions don’t come every month. Ask AI to list them and divide by 12 so you set money aside monthly.
- Saving what’s left instead of saving first. Set up your SIP or recurring deposit for the day after salary day. Then spend what’s left. This one habit matters more than any budget.
- Skipping the emergency fund. Before investing heavily, build a safety net. Our guides on why you need an emergency fund first and how to build one when money is tight explain why.
- Paying only the credit card minimum. If AI shows big credit card interest charges, clearing that debt comes before everything else. Here’s the real cost of paying only the minimum due, and how to use a credit card without ever paying interest.
- Never reviewing. A budget you made once and forgot is just a wish. Put a monthly reminder in your phone.
After the budget: what to do with your savings
Once your budget frees up money each month, put it to work in this order:
- Emergency fund: three to six months of essential expenses in a savings account, sweep-in FD or liquid fund. Our FD calculator shows what a deposit can earn.
- Insurance: your own health insurance for your family, and term insurance if anyone depends on your income.
- Clear costly debt: credit cards and expensive personal loans first. Our guide on EMI vs total interest shows why a lower EMI can cost more.
- Start investing: begin with a small SIP and increase it every year. If you can save more, here’s how to invest ₹10,000 a month.
If you’re still unsure whether to save or invest a particular amount, read saving money vs investing money.
Books that make budgeting click
AI can sort your numbers, but your money habits come from how you think about money. Two books worth reading:
- Let’s Talk Money by Monika Halan: a practical Indian guide to budgeting, insurance and investing, written in simple language.
- The Psychology of Money by Morgan Housel: short stories about why we spend and save the way we do.
Frequently asked questions
Is it safe to use ChatGPT or Gemini for budgeting?
Yes, if you share only masked data. Never share PAN, Aadhaar, account numbers, card numbers, OTPs or passwords. Share categories and amounts only, and check the app’s privacy settings.
Can AI manage my money automatically?
General chatbots can’t move money or access your bank account, and you shouldn’t give any app your banking passwords. Use AI to plan and review, and make payments yourself.
Do I need a paid AI tool for budgeting?
No. The free versions of popular AI assistants are enough for categorising spending, building a budget and monthly reviews.
What is the best budgeting rule for India?
The 50/30/20 rule is a good starting point: 50% needs, 30% wants and 20% savings. Adjust it for your rent, city and family responsibilities. Saving more than 20% is even better if you can.
How often should I review my budget with AI?
Once a month is enough for most people. A quick weekly check of small UPI payments helps if that’s where your money leaks.
Can AI give me investment advice?
AI can explain how investments work, but it is not a SEBI-registered advisor and may be wrong or outdated. Use it to learn, and verify important decisions with official sources or a registered advisor.
Your 15-minute monthly money review

Do this on the 1st of every month:
- Export last month’s bank and credit card statements.
- Mask account numbers, names and reference IDs.
- Ask AI to compare your plan vs actual spending by category.
- Cancel at least one subscription you don’t use.
- Check how your emergency fund and SIP are growing.
- Set next month’s limits and one small change to try.
You don’t need to be perfect. Riya still overspends on food delivery some months. But she knows exactly where her money goes now, and her savings have nearly tripled. That’s what a budget is really for: not guilt, but control.
Recommended reads
- Where Does Your Salary Go? A Simple Budget for Indians
- How to Build an Emergency Fund When Money Is Tight: 12 Practical Ways
- New to SIPs? Here’s How to Start With Just ₹500
- How to Invest ₹5,000 a Month in India: A Beginner’s Plan
- UPI and Online Fraud in India: How to Keep Your Money Safe
This article is for general information only and isn’t financial, tax or legal advice. AI tools can make mistakes, and rules, rates and app features change often. Please verify important details with official sources or a qualified, SEBI-registered advisor before making decisions.