Disclosure: This post has affiliate links. Arocol may earn a small commission at no extra cost to you. As an Amazon Associate I earn from qualifying purchases. Read our disclosure.
If your phone looked anything like most people’s on Thursday, it was full of red. Red screenshots of the Sensex, red headlines saying lakhs of crores were “wiped out”, and at least one relative on the family group asking whether it’s time to pull out of mutual funds before everything goes to zero.
Take a breath. A stock market crash feels personal when it’s your SIP on the screen, but a sharp fall like this one is something every long-term investor goes through many times. What matters is what you do in the next few weeks, and for most people the honest answer is: a lot less than the headlines make you want to do.
This guide explains what actually happened, why it happened, what the RBI’s rate hike means for your EMI and FD, and a simple plan for your money depending on your situation. No predictions about where the Sensex goes next. Nobody knows that, and anyone who says they do is selling something.
What happened in this week’s market crash
Here’s the short version, based on what news agencies and business papers reported between 7 and 9 October 2026. Exact figures differ a little from one outlet to another, so treat the numbers as close estimates.
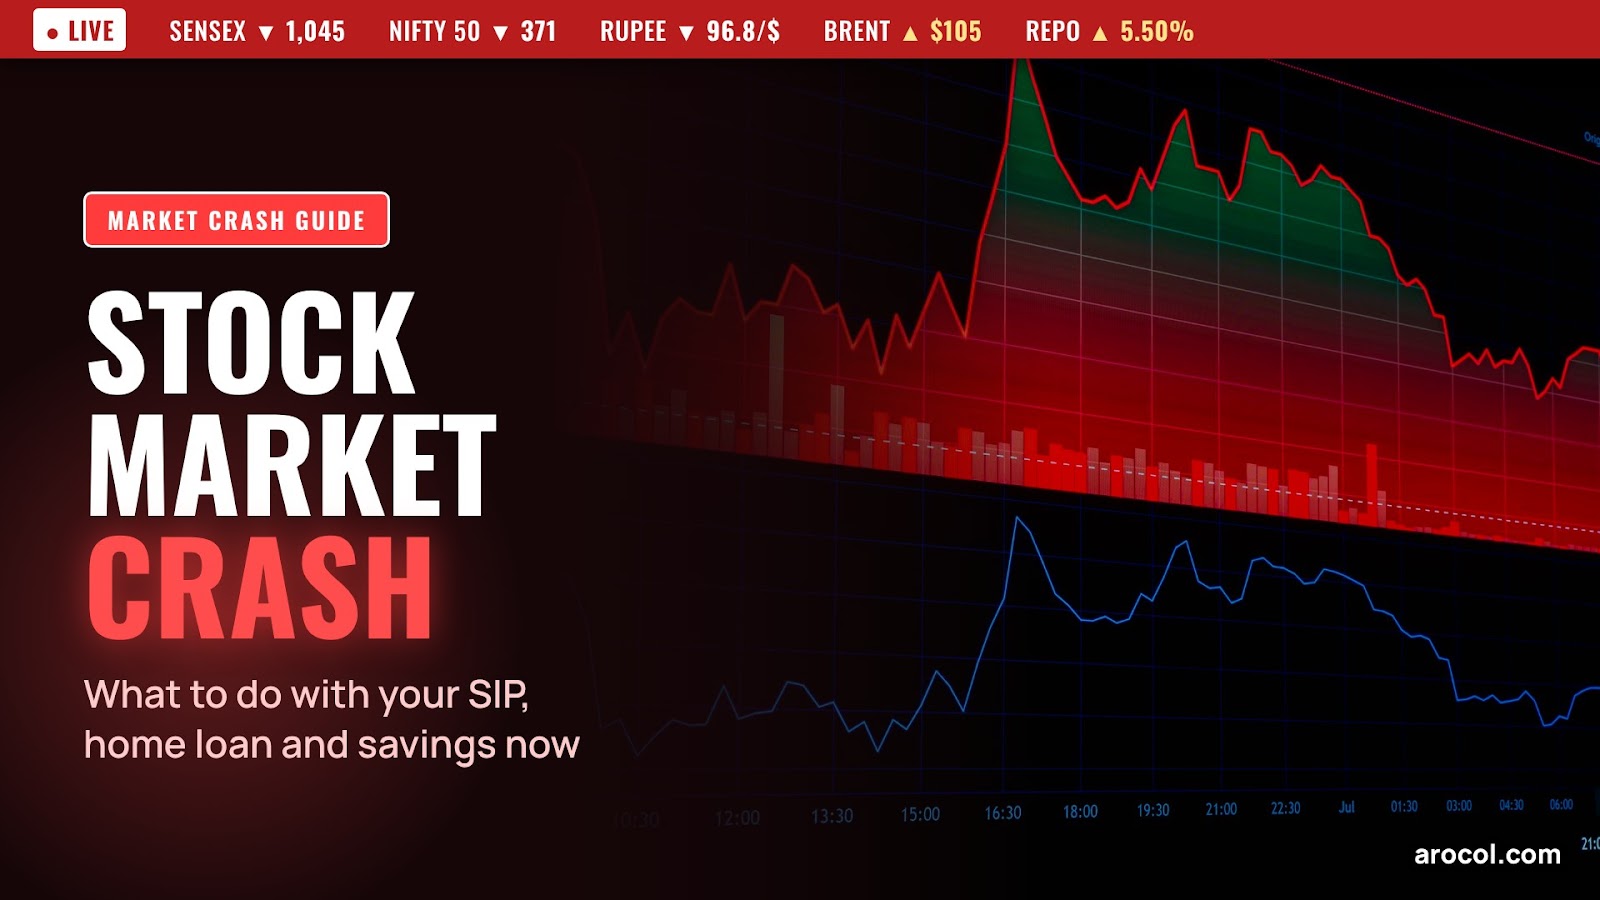
- The RBI raised rates. On 7 October, the Reserve Bank of India raised the repo rate by 0.25%, from 5.25% to 5.50%. It also changed its stance to “calibrated tightening”, which is central-bank language for “more hikes are possible, don’t expect cuts soon”. It’s the RBI’s first hike since February 2023.
- The Sensex fell more than 1,000 points on Thursday, 8 October. That’s a fall of roughly 1.4% in a day. The Nifty 50 dropped about 370 points. Reports said the Sensex closed at its lowest level in more than two and a half years.
- The total value of BSE-listed companies fell by around ₹10 lakh crore in that one session, according to PTI. Some outlets put it at ₹7 to 9 lakh crore depending on when they counted. That’s the “wealth wiped out” figure you saw everywhere.
- Oil crossed $100 a barrel. Brent crude was reported at about $105, pushed up by tension between the US and Iran.
- Foreign investors kept selling. Exchange data cited by Reuters showed foreign institutional investors sold about ₹6,121 crore of Indian shares on 7 October alone, the ninth selling session in a row.
- The rupee weakened to around 96.8 per US dollar, close to its all-time low.

Why these things knock the market down together
None of these reasons is new or mysterious. They just landed in the same week, and markets hate surprises arriving in a bunch. That’s how a normal bad week turns into a market crash.
Higher interest rates make borrowing costlier for companies and for people buying homes and cars. Slower spending can mean slower profits. Higher rates also make safe options like FDs and bonds more attractive, so some money moves out of shares.
Costly oil hurts India more than many countries, because we import most of the oil we use. When crude goes up, transport, plastics, paint, airlines and a hundred other things get costlier. That pushes inflation up, which is one reason the RBI raised rates in the first place.
Foreign investors own a big slice of Indian shares. When US bond yields rise and the rupee weakens, many of them pull money out and park it somewhere safer. Their selling alone can drag the index down for days.
Put all of that together and you get exactly what we saw: a few heavy days of selling, with big names like Reliance, HDFC Bank and Airtel falling along with almost everything else.
What “₹10 lakh crore wiped out” really means
This headline scares people more than anything else, so let’s be clear about it.
The ₹10 lakh crore is the drop in the market value of all listed companies added together. It’s the price of every share multiplied by the number of shares, before and after the fall. Nobody’s bank account lost that money. No vault was emptied.
If you own a mutual fund or shares, the value shown in your app has gone down. That’s real, and it’s not pleasant to look at. But it only turns into an actual loss if you sell at today’s price. If you hold on, the value moves with the market from here, up or down. On the day markets bounce back, you’ll see headlines about lakhs of crores “added”, and that money won’t have come from anywhere either.
Is this a stock market crash? A little perspective
Most people would call a sudden, sharp fall a stock market crash, and fair enough. But it helps to know how normal these falls are for anyone who invests for 10 or 20 years.
- In 2008, during the global financial crisis, the Nifty fell by roughly 60% from its peak. It took a few years, but it recovered and went on to new highs.
- In March 2020, when COVID lockdowns began, the Nifty fell by close to 40% in a few weeks. By the end of that same year, it was back above its old high.
- In between, there were many smaller falls of 10% to 20% that people barely remember now.
None of this guarantees the market will bounce back quickly this time. It might take months. It might fall further first. The point is simpler: falls are a regular part of owning shares, not a sign that something has broken for good. If you invest in the stock market, you’re signing up for days like Thursday, a few times every decade.
New to how the market works? Our guide to the stock market for beginners explains it from scratch.
If you have a SIP: keep it going through the crash
This is the most important part of this whole article, so here it is plainly. If you have a monthly SIP for a goal that’s five or more years away, don’t stop it because of a stock market crash.
Here’s why. A SIP puts the same amount in every month. When prices are high, that amount buys fewer units. When prices fall, the same amount buys more. A falling market is exactly when your SIP is doing its best work.

A simple example. Say your fund’s NAV was ₹100 last month, so your ₹5,000 SIP bought 50 units. This month the NAV has dropped to ₹85. The same ₹5,000 now buys about 59 units. You didn’t do anything clever. The SIP did it for you. When the market recovers, those extra units are what lift your returns.
People who pause their SIP during a fall usually restart only after the market has already climbed back. So they skip the cheap months and buy the expensive ones. That’s the opposite of what a SIP is meant to do.
If money is genuinely tight right now (a job loss, a medical bill), then yes, pause it. That’s a life decision, not a market one. Most funds let you pause for a few months without closing anything. Our SIP guide for beginners explains how pausing works.
If you were planning to start investing before the crash
Lots of people have been “planning to start a SIP” for months. Honestly, a market that’s already fallen is not a bad time to begin. You don’t need to catch the exact bottom. Nobody does.
- Start with a small monthly amount you can keep going even in a bad month.
- A simple, low-cost choice like a Nifty 50 index fund is a good first step. Our index funds guide shows how to pick one.
- If you’d rather buy ETFs or shares directly, you’ll need a demat account. You can open one with Angel One and learn the steps in our demat account guide.
If you have a lump sum sitting idle
A stock market crash tempts people to put everything in at once. “Prices are low, let’s go all in!” The trouble is that prices can keep falling for a while after you think they’re low.
A calmer approach: put the lump sum in a liquid fund and move it into an equity fund in equal parts over the next six to twelve months, using an STP (Systematic Transfer Plan). If the market keeps falling, your later instalments buy cheaper. If it recovers, at least part of your money was already in. You’ll never feel like a genius, but you’ll never feel like a fool either. Our guide on investing a ₹1 lakh lump sum walks through this step by step.
If you need the money in the next year or two
This is the one group that should act after a market crash. If you’re saving for a wedding next year, a home down payment in 18 months, or college fees that are due soon, that money shouldn’t be in shares at all, crash or no crash.
Don’t sell everything in a panic today. But over the next few weeks, start moving money you’ll need within two or three years into safer places like FDs, a liquid fund or a short-term debt fund. Do it in parts if the amount is large. The lesson for next time: the closer a goal gets, the less of that goal’s money should sit in the stock market.
What the RBI rate hike means for your home loan EMI
The stock market crash grabbed the headlines, but for many families the rate hike will matter more over the next year.

Most new home loans in India are floating-rate loans linked to the repo rate. When the repo rate goes up, your bank usually raises your loan rate too, often within a few weeks to three months.
Take a ₹30 lakh home loan for 20 years. If your rate goes from 8.5% to 8.75%, the EMI rises from about ₹26,035 to about ₹26,511. That’s roughly ₹477 more every month. Many banks don’t raise the EMI at all. They quietly extend your loan tenure instead, which keeps the EMI the same but makes you pay a lot more interest over the years.
Two things worth doing:
- Check your next loan statement to see whether your EMI or your tenure changed. If the tenure jumped, ask the bank whether you can keep the original tenure and pay the slightly higher EMI instead. Over 20 years, that choice can save you lakhs. We explain why in EMI vs total interest.
- If you have spare cash, a part-prepayment on a floating home loan is usually allowed without any penalty, and it directly cuts your interest.
The silver lining: FD rates could rise
If you’re a saver, a rate hike isn’t all bad news. Banks often raise fixed deposit rates a few weeks after the RBI does. If you have FDs maturing soon, it may be worth waiting a little or splitting your money across a few FDs with different end dates, so you can reinvest part of it at higher rates later. Short-term debt funds and liquid funds also tend to earn a little more when rates are higher.
And if you’re an NRI, a weaker rupee means every dirham or dollar you send home buys more rupees. Our guide on sending money from UAE to India compares the cheapest ways to do it.
Things not to do during a stock market crash
- Don’t sell everything because of one bad week. You’d be locking in the loss and probably buying back later at a higher price.
- Don’t borrow to “buy the dip”. Using a personal loan or credit card to invest is a fast way to turn a market fall into a debt problem.
- Don’t jump into F&O or intraday trading to “recover” losses quickly. Volatile days are when beginners lose the most. Our guide on trading vs investing explains why.
- Don’t trust WhatsApp and Telegram “tip” groups. Scammers love a stock market crash. Messages promising “guaranteed recovery” or “sure-shot stocks” are almost always traps. More on spotting them in our online fraud guide.
- Don’t check your portfolio ten times a day. It won’t change anything except your blood pressure. Once a month is plenty for a long-term investor.
The one book I’d read during a crash is The Psychology of Money. It explains why staying calm matters more than being clever. The Little Book of Common Sense Investing is another good one if you invest through index funds.
A simple stock market crash checklist for this week

- Keep your SIPs running if your goals are five or more years away.
- Check your emergency fund. Three to six months of expenses in a savings account, FD or liquid fund is what lets you ride out a fall without selling. If you don’t have one yet, build it before adding more to shares. Here’s how much emergency fund you need.
- Move money you’ll need within two years out of equity, slowly.
- Look at your home loan statement over the next couple of months and choose EMI over tenure if you can afford it.
- Leave the tip groups. Mute the noise.
If you’d like to understand the mindset side of all this (why falls feel so bad and how calm investors think), a good book on investing behaviour helps more than any news channel. You can browse a few on Amazon.
Frequently asked questions
Should I stop my SIP during a stock market crash?
Usually, no. If your goal is five or more years away and you can still afford the instalment, keeping the SIP going during a fall means you buy more units at lower prices. Stop or pause only if your own finances have changed, like a job loss.
Will the market go down further?
Nobody can say for sure. It could recover quickly, stay flat for months or fall further first. That’s exactly why it’s better to follow a plan (SIP, emergency fund, goal-based money) than to guess the next move.
Is now a good time to invest a lump sum?
Prices are lower than before the crash, but they could go lower still. Spreading a lump sum over six to twelve months through an STP is a sensible middle path for most people.
Will my home loan EMI go up after the RBI rate hike?
If you have a floating-rate loan linked to the repo rate, your interest rate will likely go up by about 0.25% in the coming weeks or months. Your bank may raise the EMI or extend the tenure instead. Check your loan statement and ask the bank which one they’ve done.
Is my money in mutual funds safe in a market crash?
Mutual funds are regulated by SEBI, and your units are held separately from the fund house’s own money, so the fund isn’t going to disappear. But the value of equity funds goes up and down with the market. A fall in value isn’t a loss of the fund, it’s a change in price.
Should I move everything to FDs after a stock market crash?
Only the money you’ll need soon. For long-term goals, FDs usually don’t beat inflation after tax. A mix that suits your timeline (shares for long goals, safer options for short ones) works better than switching everything after a bad week.
The bottom line
This week’s stock market crash came from a mix of a rate hike, costly oil, foreign selling and a weak rupee. It’s painful to watch, but it isn’t the first fall like this and it won’t be the last. Keep your SIPs going, keep short-term money safe, check your home loan statement, and stay away from anyone promising a quick recovery. The investors who do well over the long run are usually the ones who did nothing dramatic on days like Thursday.
Recommended reads
- Index Funds in India: A Simple Guide for Beginners
- New to SIPs? Here’s How to Start With Just ₹500
- Trading vs Investing in India: Which Is Right for You?
- EMI vs Total Interest: Why a Lower EMI Can Cost You Lakhs More
- Emergency Fund in India: How Much You Need and Where to Keep It
This article is for general information and education only and isn’t investment, tax or financial advice. Market figures are as reported by news agencies and business publications between 7 and 9 October 2026 and may differ slightly between sources. Mutual fund investments are subject to market risks; read all scheme-related documents carefully. Please speak to a SEBI-registered adviser about your own situation.